Mortgage Rates Just Hit a One-Year High — Here's What It Actually Costs You in Poinciana, Davenport & Kissimmee
Buyer Education
Mortgage Rates Just Hit a One-Year High — Here's What It Actually Costs You in Poinciana, Davenport & Kissimmee
If you've searched anything about mortgage rates in the last few days, you're not alone. Rate anxiety is spiking right now — the Fed just met, "FOMC" and "interest rates" are trending nationally, and every headline is some version of "rates hit a one-year high." Here's what almost nobody is telling you: what that actually means in dollars, on an actual house, in your actual zip code.
Not a national average. Not a hypothetical. Real numbers for Poinciana, Davenport, and Kissimmee, because that's what you're actually trying to figure out.
What Actually Happened This Week
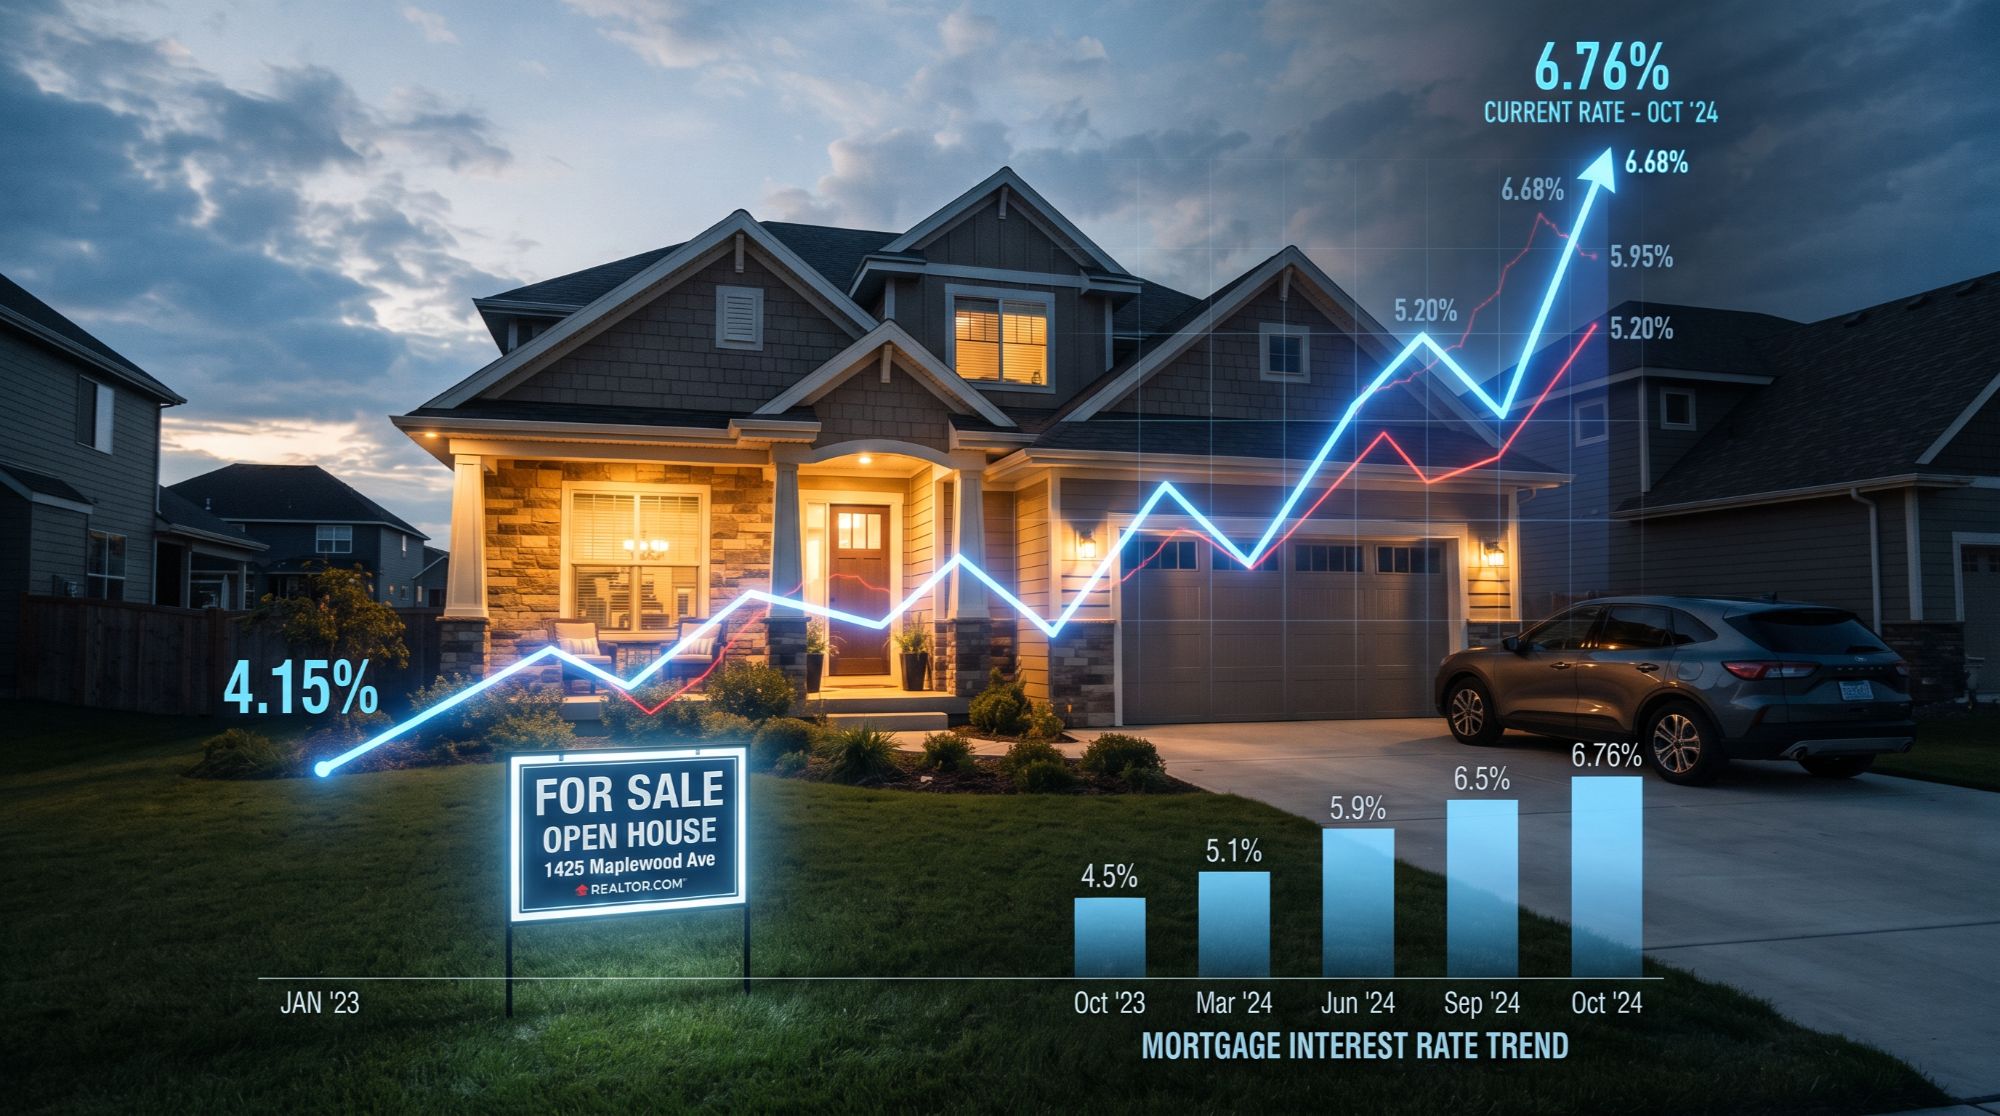
The average 30-year fixed mortgage rate climbed to 6.76% for the week, with some national lender surveys putting it closer to 6.97% — a level not seen in roughly a year. The 15-year fixed climbed too, landing around 6.09%. Both numbers moved in the same direction: up.
That's the headline. Here's the context the headline skips: rates have been bouncing in a 6.5%–7% range for most of this year. This isn't a crash or a spike out of nowhere — it's a continuation of a pattern. What changed is that we're now testing the top of that range again, which is enough to spook anyone who's been sitting on the fence waiting for "rates to come down before I buy."
That waiting strategy is exactly what I want to walk through honestly, because it's the single most common — and most expensive — mistake I see buyers make in this market.
What This Actually Costs You, In Real Numbers
Let's use real Central Florida numbers instead of a generic example. In the 34758 zip code (Poinciana), the current median home price is around $332,000. In 34759, it's closer to $277,000. So let's run both.
34758 — Poinciana · $332,000 median, 5% down
|
At 6.5% $1,994/mo |
At 6.97% $2,097/mo |
Difference: ~$103/mo · ~$37,000 over 30 years
34759 — Poinciana · $277,000 median, 5% down
|
At 6.5% $1,663/mo |
At 6.97% $1,749/mo |
Difference: ~$86/mo · ~$1,032/year
Those are real numbers, and I'm not going to pretend they're nothing. A rate move like this matters. But here's where most of the internet stops the conversation — at the scary number — instead of finishing it. So let's finish it.
These numbers are based on median prices and a 5% down scenario. Your actual payment depends on your credit, your down payment, and the specific home.
Get Your Personalized Payment Breakdown →The "Wait for Rates to Drop" Trap
Here's the search behind the search: what people actually mean when they type "should I wait for mortgage rates to drop" is "I'm scared of making the wrong financial decision, and waiting feels safer than acting."
I understand that instinct. I'm not going to tell you it's irrational — it's not. But I am going to walk you through the actual math on what "waiting" costs, because that's the half of the equation that gets left out.
Say you wait a year hoping rates drop half a point, from roughly 6.9% to 6.4%. Best case, that happens. In the meantime, two things are also moving:
First, home prices don't wait with you. Poinciana's 34758 zip is currently sitting at about 25 days on market — that's a fast-moving segment, not a soft one. Inventory tightening or price appreciation of even 3-4% over a year on a $332,000 home adds roughly $10,000–$13,000 to the price you'll pay, and that's before you factor in a lower rate saving you $100/month against a higher price costing you thousands upfront.
Second, you can refinance a rate. You can't refinance a purchase price. This is the single most important sentence in this entire post, so I'll say it again: if rates drop next year, you go get a new rate on the house you already own. If prices rise next year, there's no "price-inance" — you just pay more, permanently, for the same house.
None of this means "buy no matter what." If you're not financially ready — if your credit needs six more months of work, if your down payment fund isn't there yet, if your income situation is shaky — waiting is correct, full stop, and I'll tell you that directly if that's your situation. This isn't a sales pitch to rush anyone. It's a math problem, and the honest answer depends on which side of "ready" you're actually on.
What I won't do is let "rates might go down" be the reason you sit out a market where prices are still climbing under you. Rate risk and price risk are both real. Most content online only talks about one of them.
Trying to figure out if you're actually ready to buy, or if waiting makes sense for your situation? I built a full Buyer Road Map covering credit, down payment programs, and a step-by-step timeline — free, no obligation.
Download the Buyer Road Map →The Cost Nobody's Talking About (And I Will, In the Next Post)
If you're buying in Florida right now, there's a second number that matters as much as your mortgage rate: homeowners insurance. Central Florida premiums have climbed enough in the last few years that they now materially change your monthly payment picture — sometimes by more than a full rate-point swing would. I'm not going to bury that fact in a footnote the way a lot of local content does, because burying it doesn't help you plan. It just delays the surprise until closing week.
I'm covering that in full detail — real premium ranges by zip code, and which homes get hit hardest — in the next post, because it deserves its own space, not a rushed paragraph here. If you're house-hunting right now, ask me for insurance estimates on any specific property before you fall in love with it. It changes the math more than people expect.
What You Can Actually Do About This Rate Environment
This is the part that actually matters — because a high rate isn't a wall, it's a variable, and there are real tools to work around it depending on your situation:
FHA loans — 3.5% down, more flexible credit requirements, still one of the most accessible paths into a home in this market.
VA loans — zero down for eligible veterans and service members, typically some of the most competitive rates available right now.
Florida Hometown Heroes Program — down payment and closing cost assistance for eligible Florida workers.
Down payment assistance (DPA) — several programs active across Osceola and Polk counties. You don't need 20% down, and that myth keeps qualified buyers renting longer than they need to.
Rate buydowns — a seller-paid or builder-paid buydown can offset a real chunk of the payment difference above, depending on the listing.
Physician loans — for qualifying medical professionals, often bypass standard down payment and DTI hurdles entirely.
The point isn't that one of these definitely applies to you. The point is that "the rate is high" is not the end of the analysis — it's the start of a conversation about which of these tools fits your actual numbers.
Not sure which of these programs you actually qualify for? That's a 15-minute conversation, not a guessing game.
Book a Free Buyer Strategy Call →or text me directly at 863.223.2294
The Bottom Line — No Spin
Rates are higher right now than they've been in about a year. That's true, and I'm not going to soften it. On a median-priced Poinciana home, that's roughly an extra $100 a month compared to where rates sat earlier this year.
But "rates are high" and "you should wait" are two different statements, and conflating them is where most buyers — and most real estate content — gets it wrong. Waiting has a cost too. It just doesn't show up on a mortgage calculator, so nobody talks about it.
If you're financially ready, this rate environment is workable, and there are specific programs that can offset it. If you're not financially ready, no rate number changes that, and I'll tell you that honestly instead of pushing you toward a decision that doesn't fit your situation.
Either way, the only way to know which category you're in is to run your actual numbers — not a national average, not a rule of thumb, your specific income, your specific credit, your specific target zip code. That's a conversation, not a blog post.
I'm not going to tell you today's the perfect day to buy, because for some of you it isn't — and I'll tell you that on a call too. But if you're ready to find out where you actually stand, I'll give you real numbers, not a sales pitch.
Start Here →Educated today. Prepared tomorrow. Homeowner forever.
Bernard Jackson Jr., REALTOR® (ABR®) · LPT Realty
Categories
- All Blogs (216)
- #FearlessFriday (10)
- #MotivationalMonday (14)
- #solutionsaturday (6)
- #SoulfulSunday (7)
- #TechnologyThursday (10)
- #WellnessWednesday (14)
- 10 Steps To Know About Buying A Home In Poinciana (1)
- 10 Things To Know About Davenport (1)
- 10 Things To Know About Poinciana (2)
- 5 New Things For Poinciana For 2025 (1)
- Annual Events and Festivals in Kissimmee, Fl (2)
- Benefits of Living in Poinciana (2)
- Benefits of Selling to a Cash Buyer (1)
- Buyers (80)
- City Guides Kissimmee (16)
- CITY GUIDES: Poinciana Real Estate News & Resources (8)
- CITY STATISTICS: Davenport Real Estate News & Resources (1)
- City Statistics: Kissimmee (2)
- CITY STATISTICS: Lake Wales Real Estate News & Resources (1)
- Kissimmee Homes For Rent (5)
- Kissimmee Homes For Sale (9)
- Pros and Cons of Living in Kissimmee, FL (1)
- Renters (37)
- Retirement In Poinciana, FL (1)
- Sellers (20)
- Things To Do In Poinciana (2)
- Things To Do Near Kissimmee, FL (2)
- Things To Do NYE 2025 In Orlando and Kissimmee, FL (1)
- Truth About 20 Percent Down (1)
- What Are The Benefits of Living In Kissimmee (1)
- Your Dream House (2)
Recent Posts
GET MORE INFORMATION